Table of Contents
- What Does Commercial Dump Truck Insurance Actually Cost?
- The Seven Factors That Move Your Dump Truck Insurance Premium the Most
- Coverage Tiers: Minimum Legal vs. Fully Protected
- How Truck Age and Purchase Source Affect Your Rate
- Rate-Reduction Strategies That Actually Work
- Comparing Quotes: What to Look For Beyond the Premium
- Ready for Your Next Truck? Browse Government Surplus on Municibid
Commercial dump truck insurance typically costs $7,000 to $22,000 per truck per year. Driver history, cargo type, operating radius, truck value, and garaging location set your exact premium.
These figures are general market ranges, not quotes. Rates shift by carrier, state, and year, so treat every number below as a benchmark to test against, not a promise. Working backward from the price tag helps you judge whether a quote is fair and which levers you can pull.
What Does Commercial Dump Truck Insurance Actually Cost?
Dump trucks sit in one of the more expensive commercial auto classes. They are heavy, they carry shifting loads, they work in tight job sites, and they pull a lot of liability exposure when something goes wrong on a public road. Underwriters price accordingly.
Here are realistic annual ranges for commercial dump truck insurance, per truck, by use case:
- Owner-operator hauling construction debris, sand, or gravel: roughly $7,000 to $14,000 per year for a single truck with a clean driving record and a few years of operating history.
- Small fleet of three to five trucks: roughly $6,000 to $12,000 per truck. Fleet pricing often trims the per-unit cost, but only if your loss history and driver pool are clean.
- Municipal contractor (snow removal, road work, public-works subcontracts): roughly $8,000 to $16,000 per truck. Contract requirements often push you toward higher liability limits, which raises the premium but is non-negotiable if you want the work.
- New venture with no prior operating history: $15,000 to $22,000 or more per truck, until you build a track record.
If a quote lands far below these ranges, check what was cut. If it lands far above, ask the broker which rating factor is driving it. A single at-fault accident or a driver with a DUI can add thousands on its own.
The Seven Factors That Move Your Dump Truck Insurance Premium the Most
Carriers rate dump truck risk on a handful of variables. Some you control. Some you don't. Here they are, ranked by typical impact:
| Factor | Impact | Can you control it? |
|---|---|---|
| Driver history (MVRs, accidents, violations) | Highest | Yes, through hiring and retention |
| Payload type (sand and gravel vs. hazardous or oversized loads) | High | Partly, through the work you accept |
| Operating radius (local vs. intermediate vs. long haul) | High | Yes, through the contracts you choose |
| Truck age and GVWR | Medium to high | Yes, at purchase |
| Annual mileage | Medium | Partly |
| Claims history | Medium to high | Yes, over time |
| Garaging ZIP code | Medium | Only if you can move the truck's home base |
Driver history is the biggest lever. One driver with multiple moving violations can make a policy unaffordable or uninsurable. Most carriers pull motor vehicle records on every listed driver, and many will exclude a high-risk driver outright rather than price them in.
Payload type matters more than most new owners expect. Hauling clean fill or aggregate is cheap to insure compared with hauling contaminated soil, demolition waste, or anything that triggers environmental liability.
Know what your contracts require before you buy coverage. A policy that excludes a material you actually haul is worse than no policy.
Radius and mileage drive exposure. A truck that stays within 50 miles of home runs fewer hours on the road than one crossing state lines, and underwriters price that difference directly.
The factors you can't change quickly, like ZIP code, still deserve a quote comparison. A truck garaged in a dense metro area can cost noticeably more to insure than the same truck parked in a rural county.
Coverage Tiers: Minimum Legal vs. Fully Protected
Many owners default to the cheapest policy that satisfies the law. That is a financial gamble, so here is how the tiers of commercial dump truck insurance compare.
Tier 1: State minimums only
This is primary liability at the level your state or the FMCSA requires, and little else. It pays for damage and injury you cause to others, up to the limit. It does not pay to repair or replace your own truck.
The limits are often far lower than the cost of a serious accident. A single at-fault crash involving injuries can exceed the limit and leave you personally and corporately liable for the rest. This tier carries the lowest premium and the largest exposure gap.
Tier 2: Standard commercial package
This adds physical damage coverage (collision and comprehensive) for your own truck, higher liability limits (commonly $750,000 to $1 million), uninsured and underinsured motorist coverage, and often medical payments.
For most working owner-operators, this is the sensible baseline. It typically adds several thousand dollars a year over minimums, and it protects the asset you just paid for.
Tier 3: Full protection
This builds on the standard package with cargo coverage, a commercial umbrella policy for additional liability above your primary limits, non-owned and hired auto coverage, and sometimes downtime or rental reimbursement.
Umbrella limits of $1 million to $5 million are common for contractors working on public projects. This tier costs the most, and it is the only one that holds up under a catastrophic claim.
The real question is not which tier is cheapest. It is which gap you can afford to leave open. If losing the truck would end the business, physical damage coverage is not optional. If a lawsuit could exceed your primary limit, an umbrella is cheap relative to the exposure.
How Truck Age and Purchase Source Affect Your Rate
Carriers care about what the truck is worth, how reliable it is, and how well it has been maintained. Older trucks generally cost less to insure for physical damage because the insured value is lower, but they can draw scrutiny on liability if the underwriter suspects deferred maintenance.
Documentation helps. A truck with a clear maintenance history, inspection records, and a known operating background is easier to underwrite than one with a mystery past. Be ready to provide the VIN, purchase price, mileage, and any service records when you apply for commercial dump truck insurance.
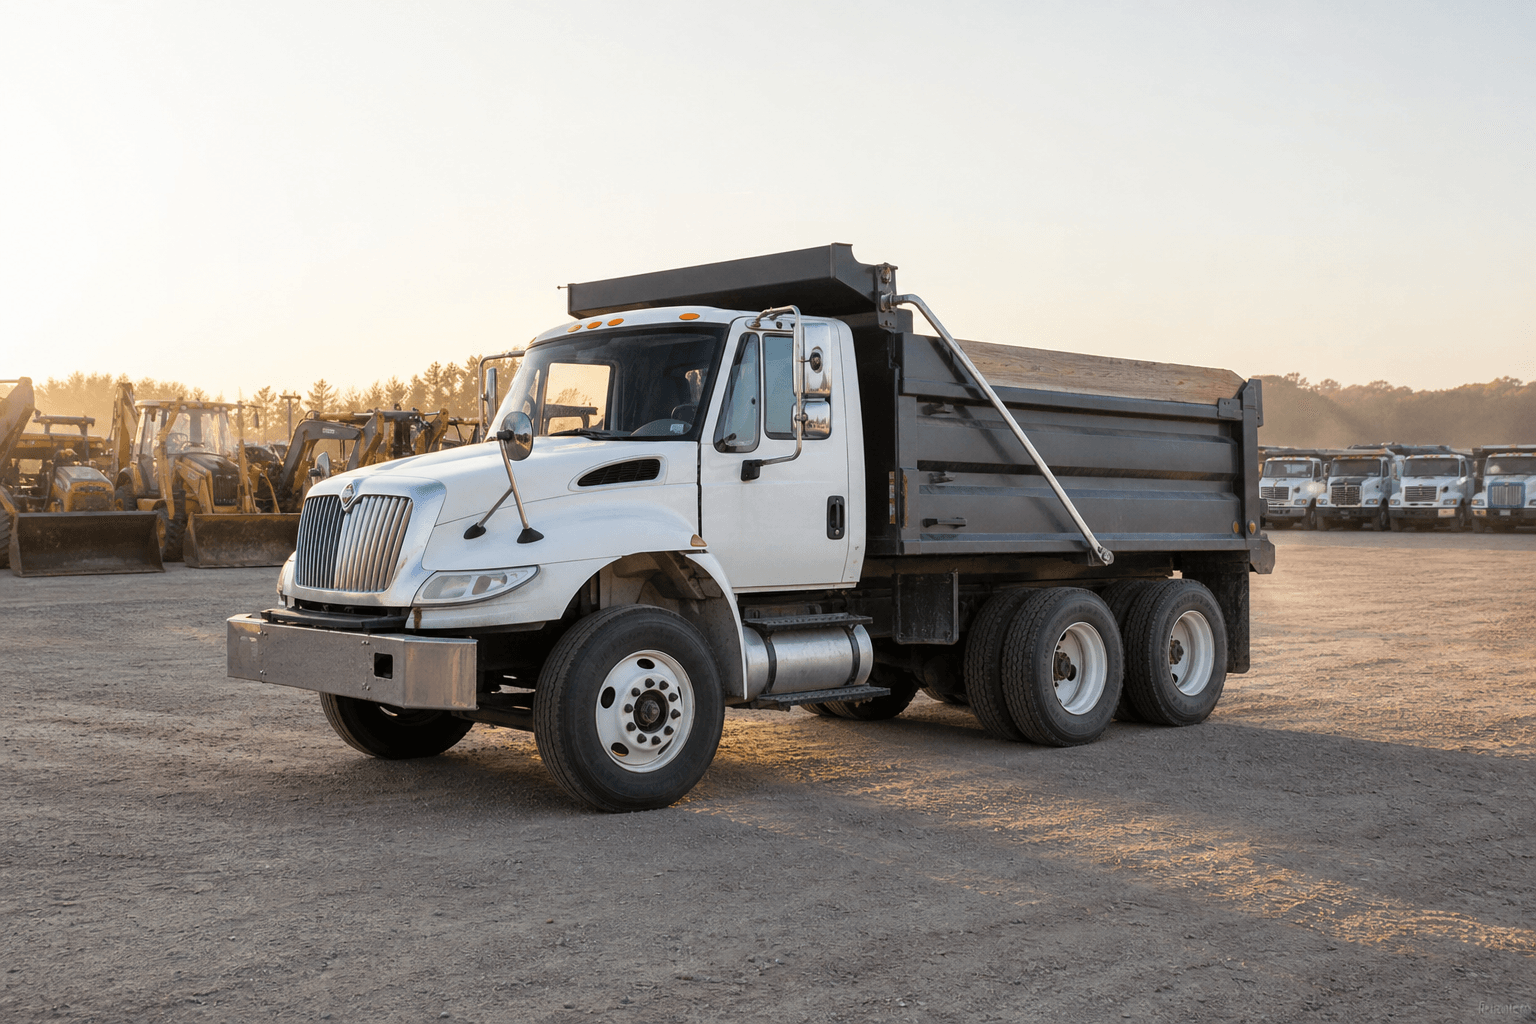
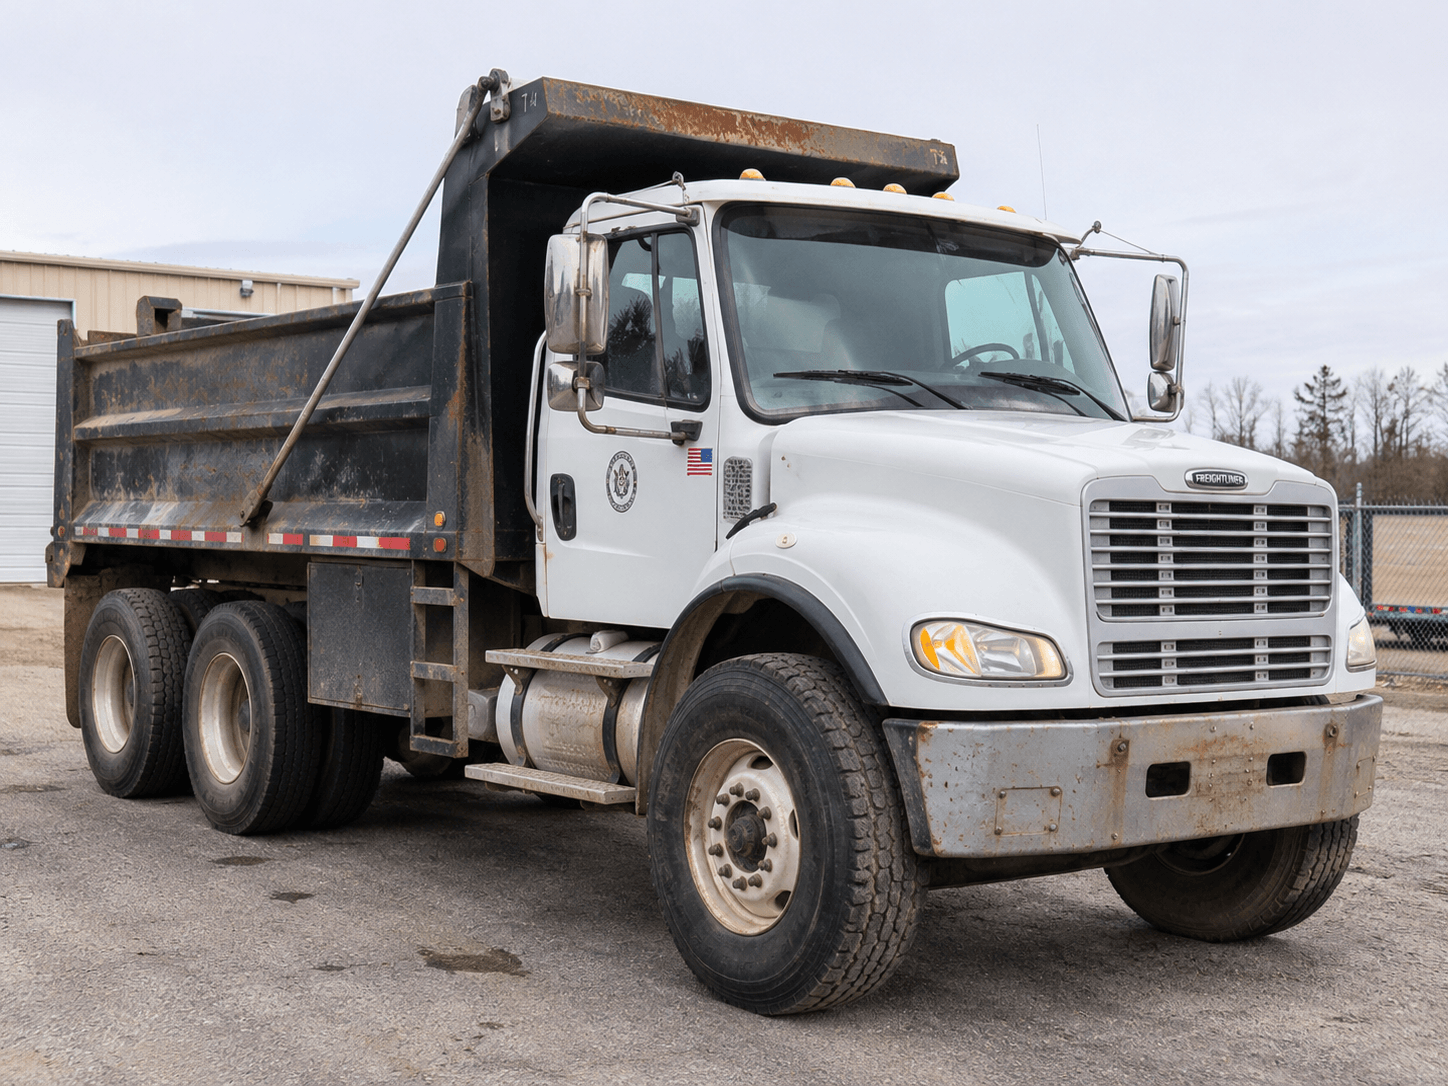
This is where the purchase source can work in your favor. Government-surplus vehicles, such as the dump trucks sold through public agencies, are often maintained on regular schedules by in-house fleet shops and tend to carry service records. They are also frequently used locally and at lower annual mileage than private-fleet trucks of the same age.
Those are traits underwriters like to see, though you should not assume every surplus unit qualifies for a better rate. Condition and documentation vary by truck. Read the listing details, ask for records where the agency offers them, and tell your broker what you have.
If you are weighing options, you can browse dump trucks on Municibid and compare age, mileage, and condition notes against what your insurer will want to see.
Rate-Reduction Strategies That Actually Work
Generic advice like "shop around" is true and useless. These tactics are specific to dump truck operations:
- Telematics and GPS monitoring. Many carriers offer discounts when you install tracking that reports speed, hard braking, and idling. It also gives you evidence if a claim is disputed.
- Driver safety training. Documented training programs, especially those covering backing, load securement, and tipping hazards, can earn credits and reduce the likelihood of the claims that raise your rates.
- Higher physical damage deductibles. Raising your collision and comprehensive deductible lowers the premium. Only do this if you can comfortably cover the deductible out of pocket on short notice.
- Bundling with general liability. If you also need a general liability policy for your contracting work, placing both with one carrier can reduce the combined cost.
- Using a specialist broker. Dump truck coverage is a niche market. A broker who regularly places hauling and construction risks has access to carriers that general agents don't, and knows which ones favor your operation.
- Tightening driver selection. Pulling MVRs before you hire, and removing drivers with recent violations from the policy, often saves more than any discount program.
- Building continuous coverage. A gap in coverage can mark you as higher risk. Staying insured without lapses helps your rates over time.
For related safety and compliance reading, the Federal Motor Carrier Safety Administration publishes requirements and resources for commercial vehicle operators at fmcsa.dot.gov.
Comparing Quotes: What to Look For Beyond the Premium
Two quotes with the same price can protect you very differently. Read them like an operator, not a shopper.
- Coverage limits. Confirm the liability limit per accident, and whether it is a combined single limit or split. Lower limits mean cheaper premiums and bigger personal exposure.
- Exclusions. Look for exclusions on specific cargo, work types, radius, or named drivers. A policy that excludes the material you haul or the job you bid on is a policy you cannot use.
- Cargo coverage. If cargo coverage is included, check the limit and what counts as covered cargo. A $200-cheaper policy with a cargo exclusion can cost you $40,000 or more at claim time.
- Sub-hauler coverage. If you ever bring in outside trucks or drivers, confirm the policy covers hired and non-owned autos and that sub-haulers carry their own proof of insurance.
- Carrier financial strength. Check the carrier's rating with AM Best. A rating in the A range signals the company can pay large claims.
- Claims-handling reputation. Ask other haulers who they use and how claims went. A cheap policy from a carrier that fights every claim is not cheap.
- Deductibles and fees. Compare deductibles across quotes and check for policy fees or audit provisions that change the true annual cost.
Request quotes in writing, on equal terms, and ask the broker to explain every difference. If a number looks too good, find out which coverage it replaced.
Ready for Your Next Truck? Browse Government Surplus on Municibid
Knowing your commercial dump truck insurance cost before you bid makes your budget more honest. A truck that looks like a bargain on the auction page can look different once you add a realistic annual premium on top of the purchase price. Run the numbers first, then bid with confidence.
Municibid lists dump trucks and other heavy equipment from government agencies throughout the year. You can explore heavy-duty trucks, dump trucks, and heavy equipment whenever you are ready. Every sale supports a public agency, and proceeds go back to the community that sold the vehicle.
If you have already bought a truck and are sorting out coverage, start by gathering the VIN, bill of sale, and any maintenance records the agency provided. Then take them to a broker who writes dump truck policies. Good paperwork and a clear plan are the fastest route to a fair quote.